UK VAT Refund Guide
A UK VAT refund may allow an eligible business or visitor to recover VAT paid on certain purchases. For EU VAT refunds, see our EU VAT refund calculator. Businesses reclaiming foreign VAT can use our foreign VAT reclaim guide.
Non-UK businesses may be able to reclaim UK VAT through HMRC’s overseas VAT refund scheme if they meet the conditions. Visitors follow different rules, and Great Britain and Northern Ireland have separate arrangements for tax-free shopping.
Before making a claim, check which scheme applies to you, keep your invoices and supporting documents, and make sure you follow the required process.
UK VAT Refund Eligibility for Visitors
Visitor VAT refunds are not available under one single UK-wide process.
In Great Britain, the VAT Retail Export Scheme ended on 1 January 2021 and is no longer available. Tax-free goods can still be purchased from retailers offering tax-free shopping for direct export.
Northern Ireland has a separate visitor refund scheme. Eligible visitors may be able to claim VAT back on qualifying goods bought from participating retailers and taken out of Northern Ireland and the EU within the required period.
The Northern Ireland scheme generally applies to people who live outside Northern Ireland and the EU. There are also specific rules for people who work or study in Northern Ireland and for certain residents who are leaving for at least 12 months.
The goods must normally be taken out of Northern Ireland and the EU by the last day of the third month after the month in which they were bought. Not every retailer participates in the scheme.
VAT Refunds When Leaving the UK
If you are using the Northern Ireland visitor refund scheme, the claim process involves several steps:
- Ask the retailer for a VAT 407(NI) form and provide proof that you are eligible.
- Complete the customer section of the form while making the purchase.
- Keep the goods and receipts with you.
- Show the goods, completed form and receipts to customs when leaving Northern Ireland or the EU.
- Get the form approved by customs.
- Send the approved form to the retailer or refund provider, or take it to a refund desk where that option is available.
- Keep copies of the completed paperwork.
If your journey includes a connection through an EU country and the goods are checked into hold luggage, the customs step must be completed in Northern Ireland when you check in.
If your journey involves a connection, check the departure procedure before travelling so you know where the goods and refund documents need to be presented.
For Great Britain, leaving the UK does not by itself create a right to reclaim VAT on goods bought in England, Scotland or Wales. The current tax-free shopping rules should be checked before purchase.
Heathrow and London VAT Refund Questions
Can I claim a VAT refund at Heathrow?
Going through Heathrow does not by itself create a VAT refund entitlement.
For purchases made in Great Britain, the old airport-based VAT Retail Export Scheme is no longer available. The current tax-free shopping arrangement is based on eligible goods being delivered directly outside the UK by a participating retailer.
Heathrow can still be relevant to Northern Ireland claims where customs documents and goods need to be checked as part of the journey. The correct procedure depends on where the goods were purchased and the route being taken.
What if I bought something in London before flying home?
If the purchase was made in Great Britain, simply taking the item to Heathrow does not create a general right to reclaim the VAT.
If the retailer offers tax-free shopping, ask about its delivery arrangement before completing the purchase. Keep any invoices or documents the retailer provides.
For a Northern Ireland purchase, a separate visitor refund scheme may apply if you meet the eligibility requirements.
UK Retailer and Apple Purchase Refund Considerations
Buying an expensive item does not create a separate VAT refund rule. This applies to products such as an iPhone, Mac, iPad or other high-value goods.
The key question is not the brand or price of the item. It is whether the purchase qualifies under the VAT refund or tax-free shopping arrangement being used.
For a purchase from a retailer in Great Britain, ask the retailer before payment whether it offers tax-free delivery outside the UK. For a qualifying Northern Ireland purchase, make sure the retailer provides the required VAT refund paperwork and that you understand the customs process.
Keep the itemised invoice, refund form and any other documents supplied by the retailer. These records may be needed when the claim is processed.
UK VAT Refund Amounts and Fees
The amount you receive depends on the amount of eligible VAT and the rules of the refund scheme. A refund is not always equal to every pound of VAT shown on a receipt.
For Northern Ireland visitor refunds, retailers or commercial refund providers may charge a handling fee. The fee is normally deducted from the refund paid to the visitor.
| Refund Situation | What Affects the Amount |
| Non-UK business | Eligible UK VAT paid on qualifying purchases or imports, subject to HMRC conditions |
| Northern Ireland visitor | VAT on qualifying goods taken out of Northern Ireland and the EU |
| Retailer or refund-provider fee | May reduce the amount paid to the visitor |
| Partly recoverable VAT | Only the eligible portion may be reclaimed |
| Ineligible purchase | VAT outside the relevant scheme cannot be reclaimed |
| Refund calculation | Based on eligible VAT rather than total spending |
The exact amount can also depend on whether the purchase is fully eligible, whether part of the VAT is excluded, and whether the refund provider applies a charge.
UK VAT Refunds for Non-UK Businesses
A business established outside the UK may be able to reclaim UK VAT through the overseas VAT refund scheme.
HMRC’s current conditions include:
- The business is established outside the UK.
- It is not registered, liable or eligible to be registered for UK VAT.
- It has no business establishment or other fixed establishment in the UK.
- It does not make supplies in the UK, apart from certain specified supplies.
- The business’s home country provides comparable VAT refund arrangements for UK businesses.
The scheme can cover eligible VAT on goods and services used in the UK and certain imports into the UK. Specific exclusions and recovery rules can apply, so a business cannot assume that every amount of UK VAT it pays will be refundable.
VAT Refund Claim Periods and Deadlines
The standard prescribed year for the overseas VAT refund scheme runs from 1 July to 30 June.
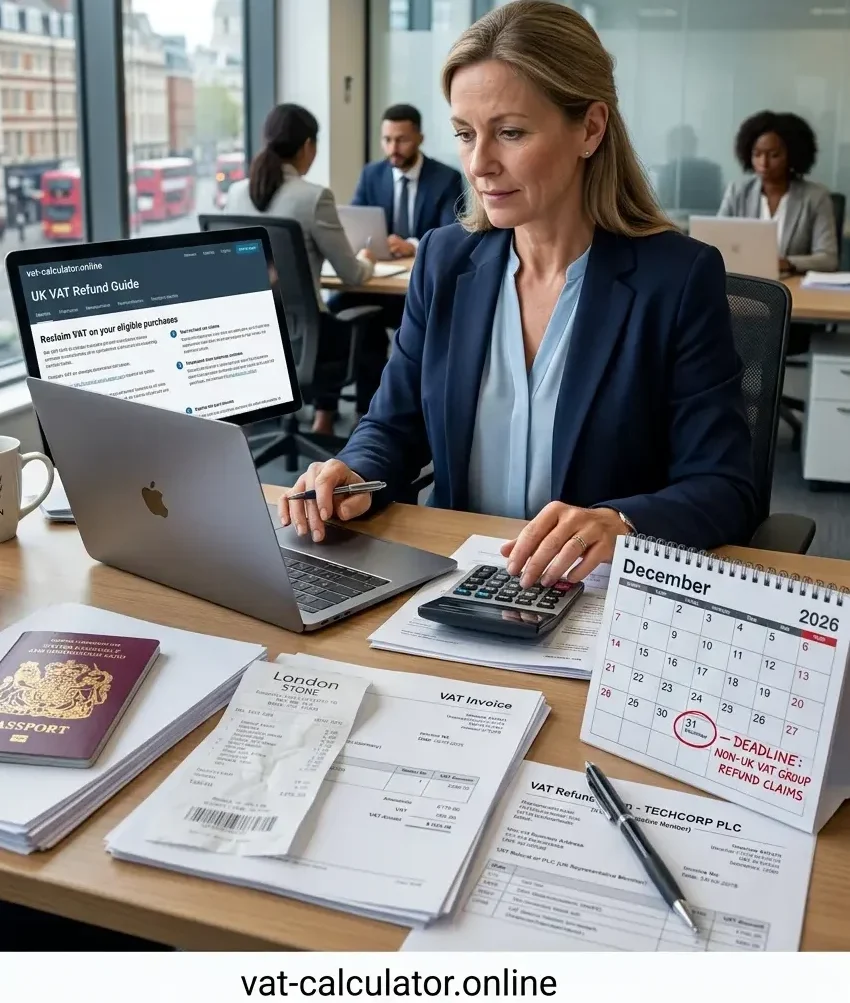
Claims normally need to be submitted by 31 December following the end of the prescribed year. For example, a claim covering the period from 1 July 2025 to 30 June 2026 normally has a deadline of 31 December 2026.
Claims covering less than the full prescribed year are subject to minimum period and minimum claim-value rules. For a claim covering at least three calendar months but less than the full prescribed year, the minimum amount is £130. The minimum is £16 when the claim covers the full prescribed year or the remaining part of the prescribed year.
Businesses should check the current HMRC rules before submitting a claim because the conditions depend on the period being claimed.
Documents Needed for a Non-UK VAT Refund Claim
A non-UK business may need to provide:
- VAT65A application form
- Certificate of status
- VAT invoices
- Supporting documents
- Information showing that the business meets the refund conditions
The invoices and other supporting records should be kept in case HMRC needs to verify the claim.
HMRC allows eligible businesses to submit claims electronically through its secure file-transfer process. Businesses need to register for the service before submitting an electronic claim.
UK VAT Refunds for Businesses in a VAT Group
HMRC changed the rules in September 2026 for non-UK businesses that are members of a VAT group.
Each eligible non-UK business must now submit its own claim for UK VAT that it incurred. HMRC will no longer accept a claim from the VAT group’s representative member unless that representative member incurred the VAT itself.
There is a transitional arrangement for VAT incurred during the 2025 to 2026 prescribed year, covering 1 July 2025 to 30 June 2026. For that period, HMRC will accept a claim from either the individual VAT group member that incurred the VAT or the representative member.
The deadline for these 2025 to 2026 claims is 31 December 2026.
Businesses affected by this change should check the latest HMRC guidance before submitting a claim.
FAQs
Final Thoughts
A UK VAT refund depends on who is making the claim, where the purchase was made and which refund arrangement applies.
Visitors need to distinguish between Great Britain and Northern Ireland, while non-UK businesses follow a separate HMRC refund process. The eligibility conditions, documents and deadlines are different for each type of claim.
For Northern Ireland visitor refunds, keep the VAT 407(NI) form, receipts and goods available for the required customs checks. For non-UK businesses, check the HMRC